If your roof claim was denied in Texas, start with the written reasons your insurer must give you, then compare them with independent photos of the roof. Many denials and lowball payments come down to wear-versus-hail calls, missed slopes or missing line items, and a documented re-inspection request is often the first fix worth trying.
A denial letter after a hailstorm feels final. Usually it is not. Insurers deny or underpay roof claims for a handful of recurring reasons, and several of them can be addressed with better evidence. Before you accept the decision or escalate, it helps to know which situation you are in.
Common Reasons for a Denied Hail Claim
A denied hail claim, or one paid far below what the roof needs, usually traces back to one of these:
| Reason given | What it usually means | What can help |
|---|---|---|
| Wear and tear or age | Adjuster judged the marks as normal aging | Photos separating hail hits from wear |
| Not enough damage | Test-square counts fell below the insurer's threshold | Evidence from slopes or squares not counted |
| Below the deductible | Approved repairs cost less than your deductible | A fuller scope if items were missed |
| Cosmetic damage only | Policy excludes appearance-only damage | Proof of functional damage, such as leaks or cracks |
| Prior or unrelated storm | Damage linked to an earlier date | Dated photos and storm reports matching your date of loss |
| Late notice | Claim reported outside the policy's terms | Facts showing when the damage was discovered |
| Installation or defect issue | Problem blamed on workmanship or the product | Manufacturer or installation records |
Underpaid Roof Claims Count Too
An underpaid roof claim is more common than an outright denial. The estimate may approve some slopes but not others, or leave out items that any full replacement needs: drip edge, starter strip, ridge caps, pipe boots, ventilation, permit fees, or removal of a second layer of shingles. On a replacement cost policy, part of the payment may be held back as depreciation until the work is done. That is normal, but it can look like an underpayment if no one explained it.
Want a roofer to look at it?
Free inspection with photos. Se habla español.
- 5.0 on Google (33 reviews)
- Free inspections & estimates
- Se habla español
- Workmanship guaranteed in writing with every contract
Steps to Take After a Roof Claim Denied in Texas
Work through these in order:
- Read the letter closely. Texas Insurance Code Chapter 542 requires an insurer that rejects a claim to state its reasons in writing. Those reasons tell you what evidence matters.
- Get the adjuster's estimate and photos. Ask for the full report if you only received a summary.
- Get an independent inspection. A roofer who did not write the first report can check whether hail damage was missed.
- Send a re-inspection request in writing. Attach photos, describe what you believe was missed, and ask for a second visit.
- Request a supplement for missing items. If the claim was approved but short, list the missing line items with photos.
- Consider appraisal for amount disputes. If you agree there is damage but not on its value, check your policy's appraisal clause.
- Contact TDI. The Texas Department of Insurance help line, 1-800-252-3439, answers questions and takes complaints.
How a Roof Claim Appeal Usually Works
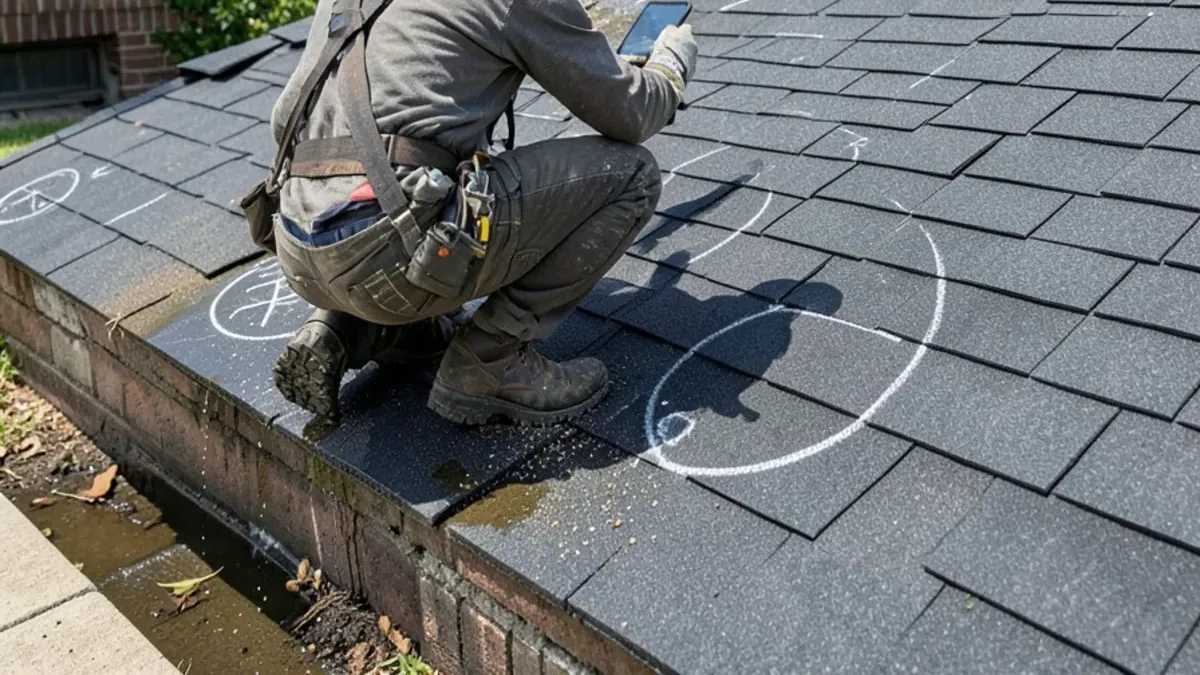
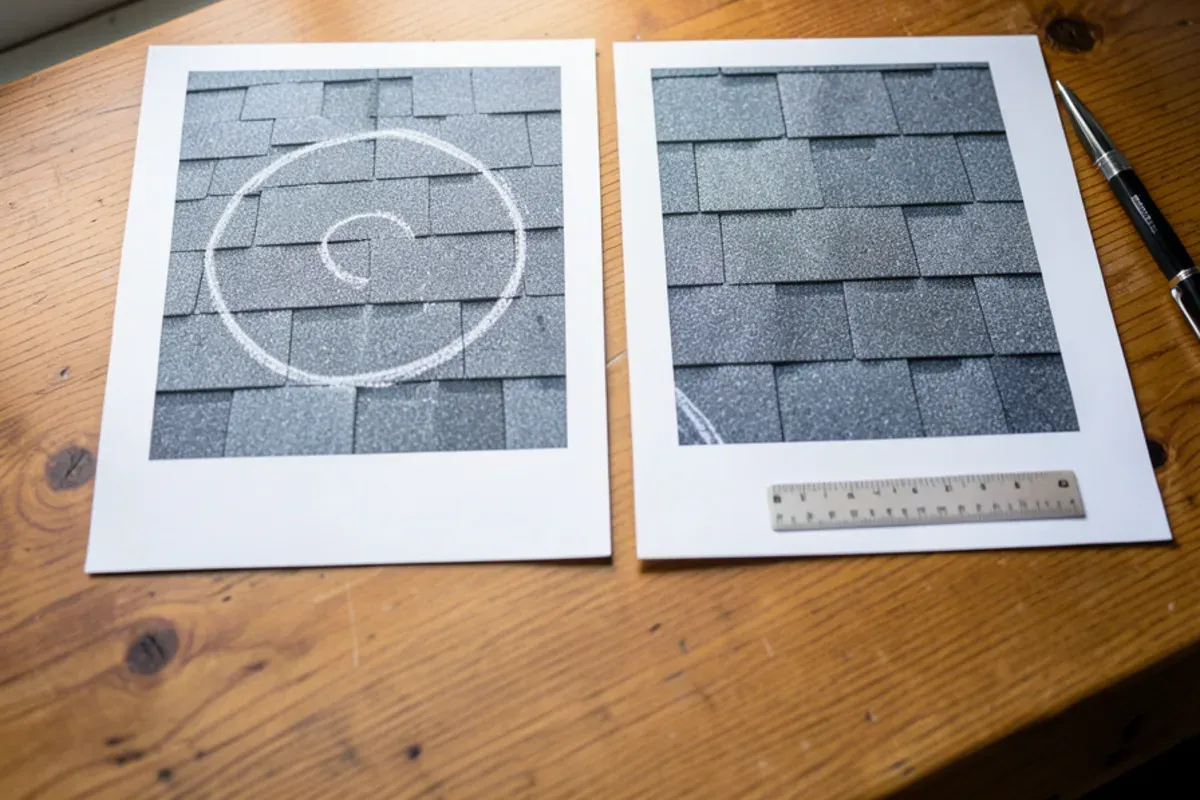
Insurers rarely use the word appeal, but a roof claim appeal in practice is a written request for reconsideration backed by new evidence. A re-inspection request is the most common version. What helps most is specific evidence: photos of individual hits with chalk circles and scale, soft-metal dents that match the storm, and a slope-by-slope summary. Our denied claim re-inspection service produces exactly that kind of report.
What to Put in a Re-Inspection Request
A re-inspection request works best when it reads like a short, specific report rather than a complaint. Before you send yours, check that it covers each of these:
- Claim number, policy number, property address and the date of loss exactly as the insurer has it
- The date of the first inspection and the adjuster's name
- A one-line summary of what you believe was missed, slope by slope (for example, "rear west slope not inspected")
- Photos with scale and chalk marks, each labeled with the slope and the date taken
- Soft-metal dents that match the storm, such as vent caps or ridge vent on the same slopes
- Any interior water damage that appeared after the storm, with dates
- A list of missing line items if the claim was approved but short
- A clear ask: a second inspection, with your roofer present if you want one
Send it in writing, by email or the insurer's portal, so there is a date stamp. Keep a copy of everything you attach.
What a TDI complaint can and cannot do
If the insurer does not respond, or you believe it did not follow Texas claim-handling rules, you can file a complaint with the Texas Department of Insurance online or through its help line. TDI asks the company to respond and looks at whether it followed the law and the policy. It is not a court, though, and it generally does not decide how much a disputed roof is worth. For a disagreement over the amount, appraisal, a public adjuster or an attorney are the tools built for that.
When a Public Adjuster or Attorney Makes Sense
Some disputes need someone who can act on your behalf. In Texas, that is a public adjuster holding a license from TDI under Insurance Code Chapter 4102, or an attorney. Roofing contractors may not act as public adjusters, so if a roofer offers to "handle" your appeal, that is a warning sign. If you are considering a lawsuit over a weather-related claim, Chapter 542A generally requires written notice to the insurer at least 61 days before filing, and policies contain their own suit-limitation terms. An attorney can tell you which deadlines apply.
What We Find on Re-Inspections
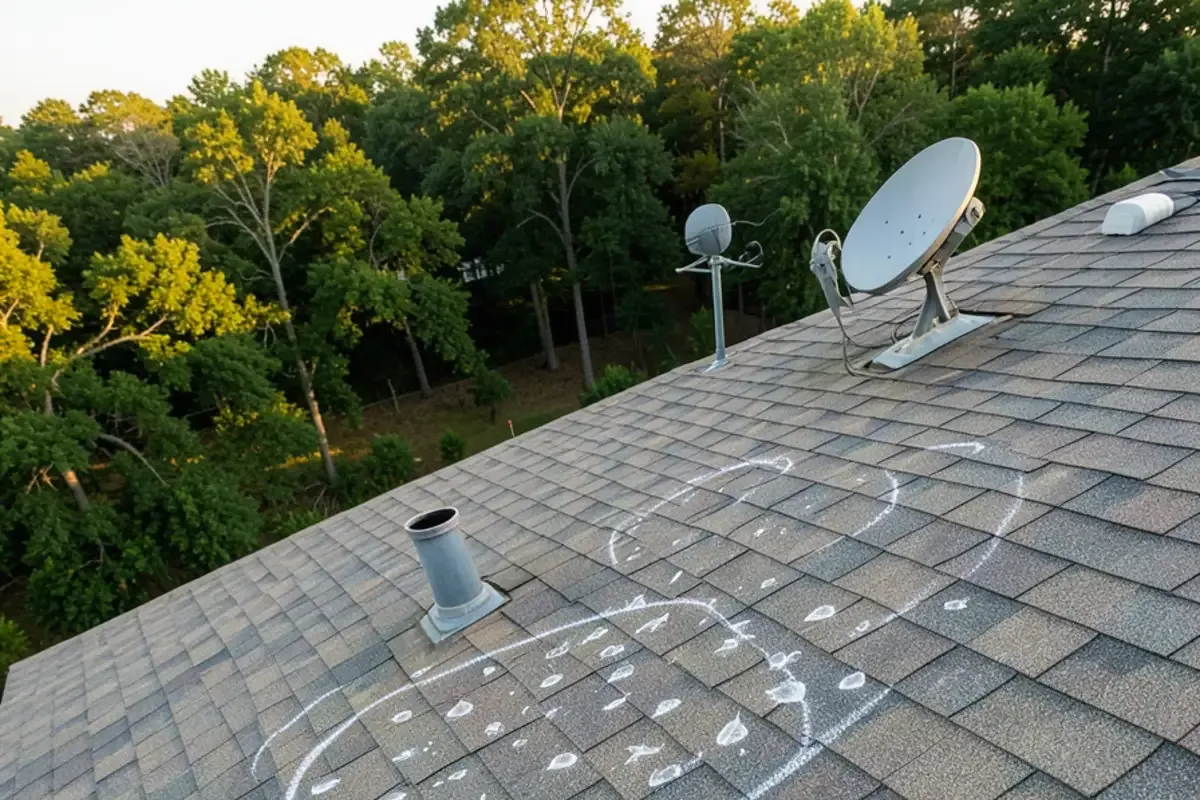
When we look at roofs after a denial, the most common issue is not a disputed opinion but an incomplete look. Back slopes that were never walked, test squares drawn in sheltered spots, or a steep second-story section skipped for safety. We also see claims denied as wear where both are present: an aging roof that also took fresh hail. Separating the two in photos often changes the conversation.
Engineer reports deserve a word of their own. When an insurer's engineer concludes the marks are wear or manufacturing blisters, a roofer's photos alone may not move the decision, because courts have generally treated a qualified engineer's report as a reasonable basis for an insurer's call. If the money at stake is large, the honest advice is that your rebuttal may need its own engineer, paired with a weather record for the date of loss. For a modest claim, that cost can outweigh what you would recover, and we will help you weigh it.
Sometimes our re-inspection agrees with the insurer, and we say so. That saves you time and gives you a clear picture for planning repairs or replacement instead. Homeowners in Dallas and across the area get the same straight answer from us either way, in English or Spanish; si su reclamo de techo fue negado, revisamos el techo y le explicamos lo que encontramos.
Keep the Process Moving
A denial is a decision based on what one inspection saw. If that inspection missed something, documented evidence is the way to reopen it. Our roof insurance claims page explains where we fit in the process, or you can ask an Irving roofing contractor for a second look at the roof. Ring (725) 745-8803; the inspection is free and the answer will be honest.
Questions readers ask
Can I get my roof claim reopened after a denial?
What is the appraisal clause in a Texas homeowners policy?
Should I hire a public adjuster for a denied roof claim?
Will a denied roof claim count against me when my policy renews?
Sources
- Texas Department of Insurance — Consumer help and complaints (1-800-252-3439)
- Texas Insurance Code Chapter 542 — Prompt payment of claims
- Texas Insurance Code Chapter 542A — Weather-related property claims
- Texas Department of Insurance — Bulletin B-0026-17
- Texas Insurance Code Chapter 4102 — Public insurance adjusters
Written by the RJ Premium Roofing team, a bilingual roofing contractor based in Irving, TX. We inspect, repair and replace roofs across Dallas–Fort Worth and document storm damage for homeowners’ insurance claims.